
Data center mergers and acquisitions hit a record high of more than $69 billion in 2025, analysis from S&P Global Market Intelligence has found.
This figure, which encompasses 113 data center deals completed last year, beat 2024’s figures by $8 billion.
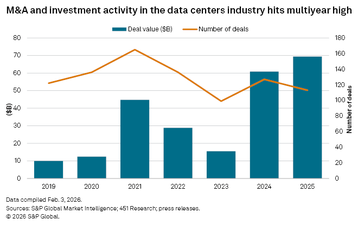
The overall volume of transactions trended down year-on-year, meaning the record-breaking figure was driven by a surge in significant transactions, including the $40 billion acquisition of Aligned Data Centers LLC by BlackRock and MGX – the largest of its kind in the digital infrastructure space.
According to S&P’s data, M&A and investment activity in the industry has risen dramatically in recent years, jumping from around $15 billion in activity in 2023 to more than $60 billion in 2024.
The next highest activity period in the past decade was a spike in 2021, caused in large part by the $15 billion acquisition of CyrusOne by KKR and Global Investment Partners, as well as more than 160 deals in total.
S&P noted that there were 32 data center-focused infrastructure funds launched in 2025, also a new record. There were fewer new infrastructure funds overall, meaning that data center-focused funds are representing a larger share.
Analyzing this data, S&P found that investment is largely coalescing around data centers with secured power availability. Critical power constraints are becoming a significant problem in building new AI infrastructure, and those data centers with already secured power are in turn able to attract higher valuations – the acquisition of Aligned Data Centers is an example of this, S&P said.
S&P’s analysis also identified that neocloud funding tripled in 2025 from record numbers in 2024, reaching more than $35 billion.
However, S&P said that neoclouds were in an “unenviable position,” as the improving availability of chips has eroded one of their key advantages. The research firm warned that heavy spending is driving increased scrutiny of the neocloud model, and a future demand or supply shock could “trigger a wave of consolidation” or create acquisition opportunities for hyperscalers.
Many neoclouds seem undeterred and, despite these challenges, continue to spend heavily and load up on ever-increasing amounts of debt to finance their business model. Yesterday, for example, Australian neocloud Firmus announced a new $10 billion debt financing facility for its “Project Southgate” AI factory platform.
Recent reporting from other research firms has shown that neocloud revenue continues to rise dramatically, with growth cresting 200 percent between 2024 and 2025. Led by CoreWeave, neoclouds are eating into the overall cloud infrastructure services market share, though they still have a long way to go before they can begin to threaten the big three (Amazon, Microsoft, Google).


Comments